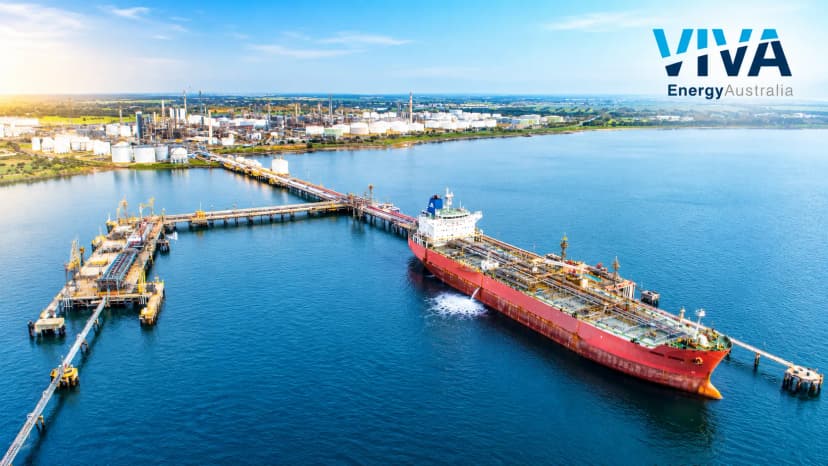
Viva Energy delivered a strong 1H26, with EBITDA and free cash flow surging on exceptional refining margins. However, earnings remain exposed to refinery cyclicality and operational risks, making normalised EPS of A$0.20–A$0.25 more appropriate for sustainable valuation.