Fortescue (ASX: FMG) shares have rebounded on stronger iron ore prices, improving Chinese demand and solid shipments. Sentiment is also lifted by dividends and production strength, while its green energy transition and decarbonisation plans support long-term growth above A$20 momentum.
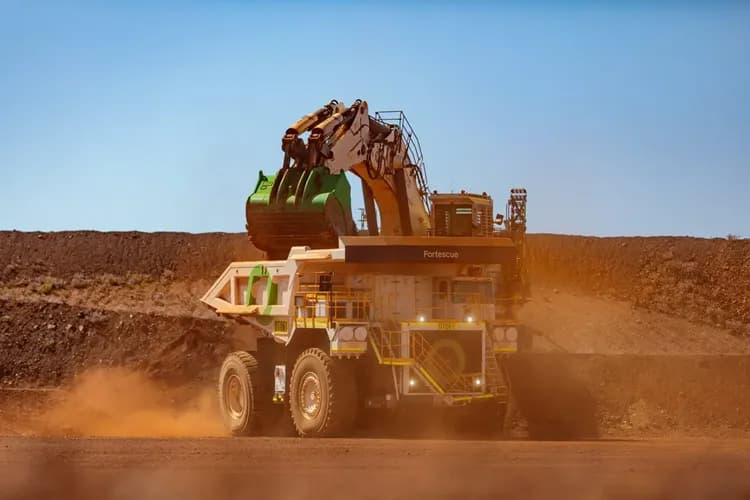
Fortescue Ltd is a low-cost iron ore producer with strong cash flow and attractive fully franked dividends, but earnings remain highly exposed to iron ore prices and Chinese demand. Trading around mid-cycle valuation levels, the stock looks fairly valued, with upside dependent on stronger commodity prices and successful expansion into magnetite and green energy.
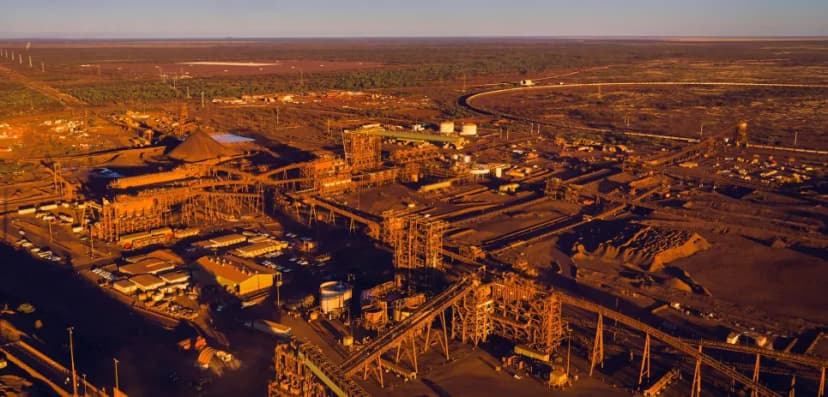
In our assessment, FMG is neither a simple iron ore beta nor a speculative green-energy experiment. It is a structurally low-cost, high-free-cash-flow industrial platform that deliberately uses surplus mining rents to accumulate long-dated strategic options in energy and decarbonisation. FY25 and the September 2025 quarterly update reinforce our view that Fortescue remains one of the most financially resilient miners globally, even as it operates in a more volatile commodity and macro environment.