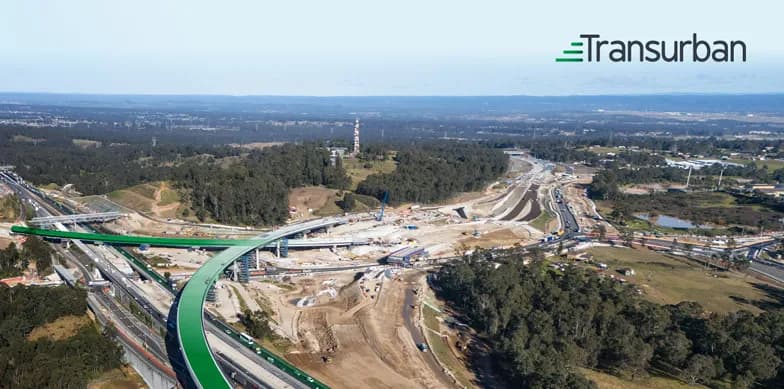
Transurban is a high-quality global infrastructure franchise with long-duration, inflation-protected cash flows, strong pricing power and irreplaceable assets. The market remains overly focused on macro headwinds, overlooking the durability of its concessions, recovering mobility and improving cash-flow conversion. As operational risk declines and cost pressures fade, Transurban is well positioned to deliver asymmetric upside through FY26–FY28 via compounding distributions and operating leverage.