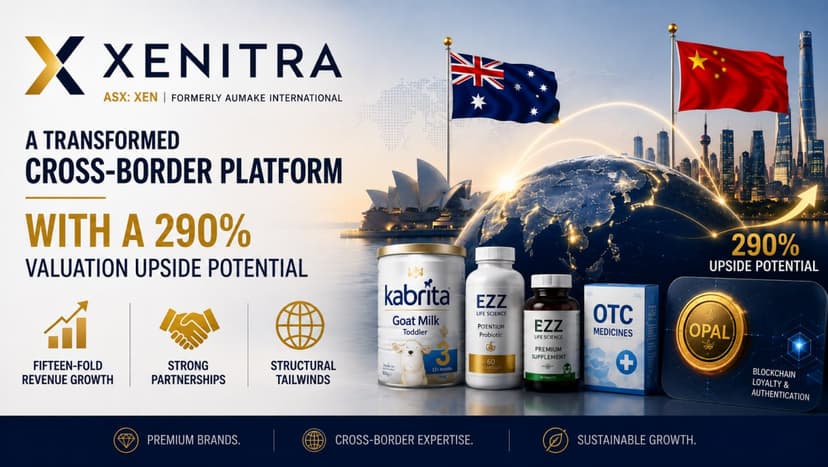
Xenitra (ASX: XEN) has transformed from a tourism-dependent retailer into a diversified cross-border platform connecting Australian and New Zealand health and consumer brands with Greater China. Revenue has grown roughly 15-fold from A$2.7m in FY23 to A$39.8m in FY25, while the company remains valued at only ~0.3x FY25 sales. With growth across nutritionals, OTC medicines and its OPAL platform, supported by major partnerships and favourable Chinese market tailwinds, Xenitra appears positioned for significant margin and earnings growth. A DCF valuation of A$0.0096–A$0.0137 per share implies substantial upside from the current A$0.003 share price.