Premier Investments (ASX: PMV): Defensive Strength Meets Dividend Momentum
Premier Investments (ASX: PMV) delivers resilient earnings, strong cash generation, and a reinstated dividend amid retail headwinds. Its diversified brand portfolio and disciplined capital management underpin long‑term shareholder value.

Carma’s (ASX: CMA) Sales Are Surging, but the Chart Still Screams Trouble
Carma’s sales growth is accelerating, but its share price remains under pressure. Strong deliveries and expanding operations stand in contrast to weak momentum, cash burn concerns, and a bearish chart setup, unless CMA breaks resistance with strong volume

Myer Holdings (ASX: MYR): Growth Strategy and Margin Resilience Through Integration
Myer Holdings (ASX: MYR) delivers strong 1H26 sales growth, disciplined cost control, and record cash generation, reinforcing operational momentum and strategic execution across its integrated retail and apparel platform.
IDP Education (ASX: IEL): Transformation and Yield Recovery Amid Policy Headwinds
IDP Education (ASX: IEL) delivers disciplined cost control and yield growth amid policy‑driven volume pressure, positioning for recovery through transformation, AI‑enabled efficiency, and upgraded FY26 EBIT guidance.
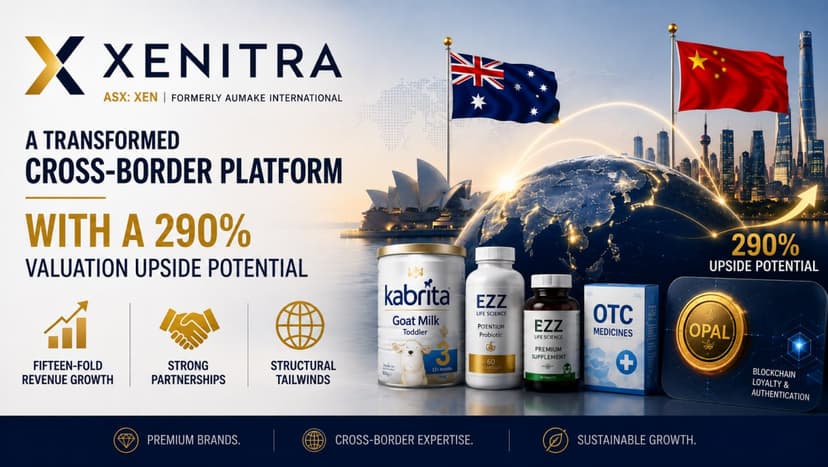
Xenitra, ASX: XEN (formerly AuMake International): A Transformed Cross-Border Platform with a 290% Valuation Upside Potential
Xenitra (ASX: XEN) has transformed from a tourism-dependent retailer into a diversified cross-border platform connecting Australian and New Zealand health and consumer brands with Greater China. Revenue has grown roughly 15-fold from A$2.7m in FY23 to A$39.8m in FY25, while the company remains valued at only ~0.3x FY25 sales. With growth across nutritionals, OTC medicines and its OPAL platform, supported by major partnerships and favourable Chinese market tailwinds, Xenitra appears positioned for significant margin and earnings growth. A DCF valuation of A$0.0096–A$0.0137 per share implies substantial upside from the current A$0.003 share price.
Bapcor (ASX: BAP)'s Double Signal: Turnaround Gains Traction Meets a Multi-Month Breakout
Bapcor’s FY26 turnaround shows improving sales momentum, lower debt, tighter pricing controls and stronger stock availability, though weak earnings, execution risks and cost pressures mean the recovery still needs further proof.